

- Live Nation Entertainment (NYSE:LYV) reports record Q3 results, with all core segments posting double digit adjusted operating income growth.
- International markets contribute strongly in the quarter, with concert attendance outside the U.S. accelerating compared with prior periods.
- Sponsorship and advertising revenues grow at a double digit rate, supported by higher brand activity across non U.S. festivals and venues.
- Management highlights record Q3 performance and faster international momentum as part of a broader story this analysis explores further. Our analysis turns up 2 other big wins for Live Nation Entertainment as well.
For readers interested in more ideas around live entertainment exposure and related income streams, the next place to look is 8 dividend fortresses.
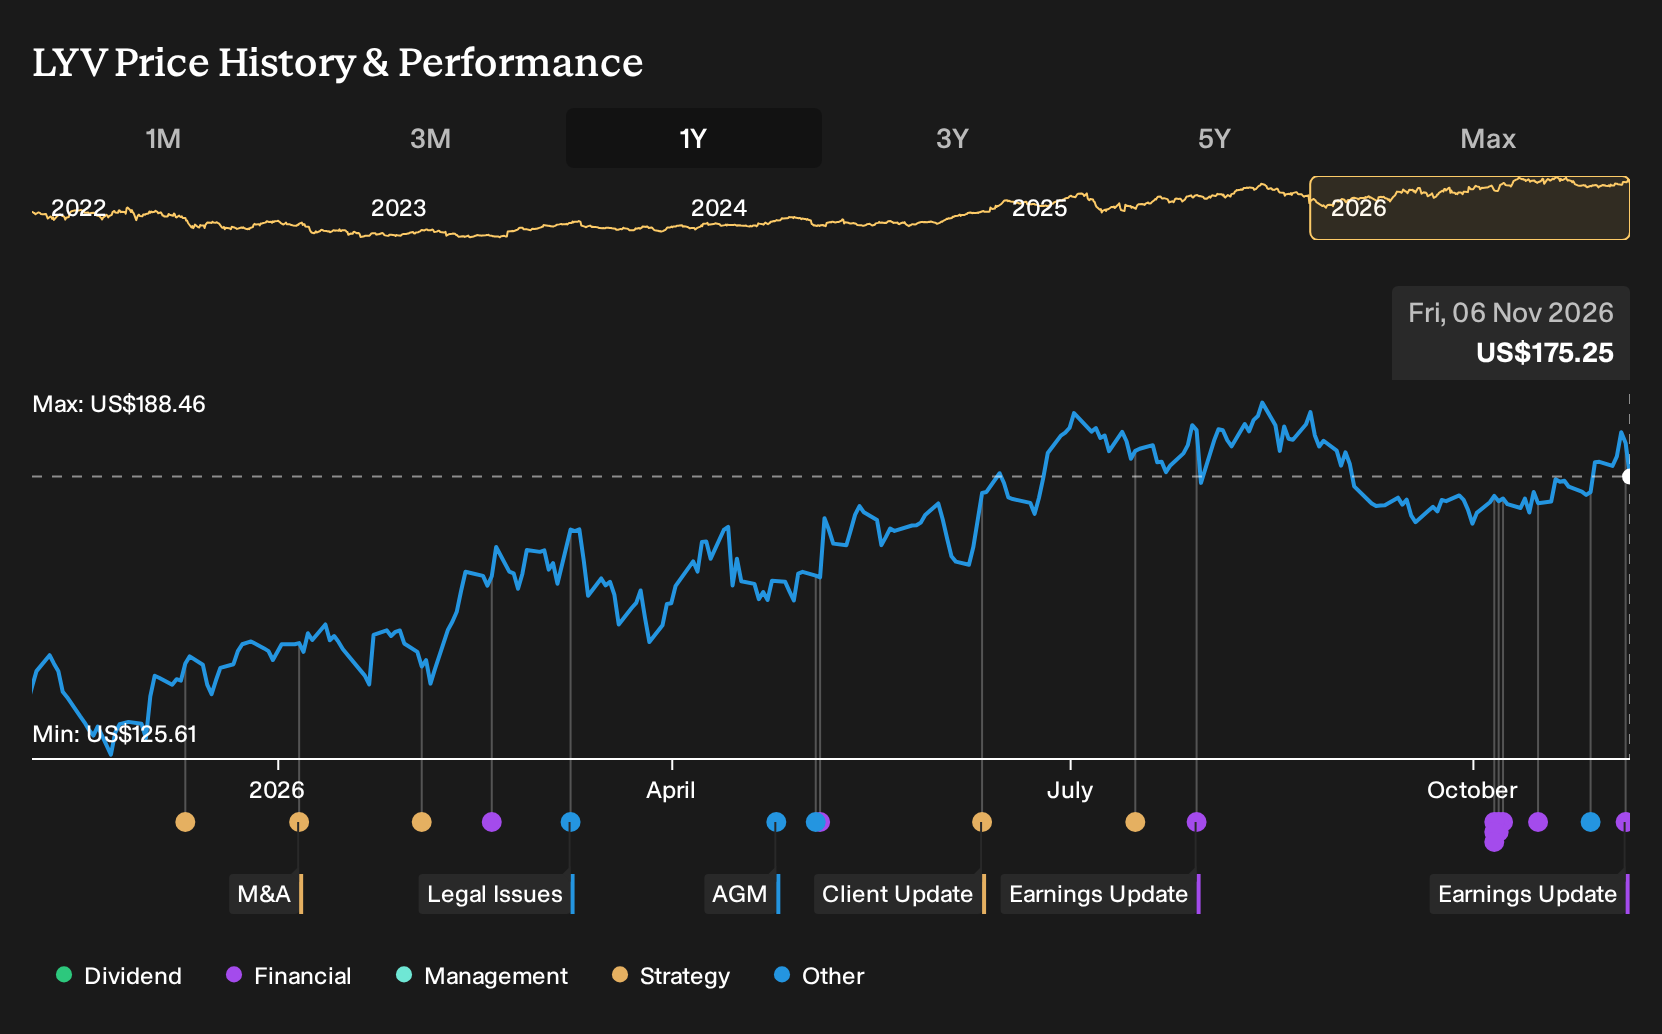
Live Nation Entertainment runs concerts and live events around the world, so record Q3 figures rely heavily on how effectively this promoter, ticketing operator, and venue manager taps global demand for in person experiences across its international footprint.
See which insiders are buying and selling Live Nation Entertainment following this latest news.
Record Q3 nudges Live Nation’s bull case ahead of the courtroom overhang
This Q3 beat nudges the Live Nation Entertainment Narrative toward the bullish side of the ledger. Revenue of US$10.1b and net income of US$447.8m for the quarter support the idea that international fan demand, venue expansion and Ticketmaster scale are contributing meaningfully to the income statement. It speaks directly to the catalysts around underpenetrated overseas markets and higher venue throughput, while the regulatory and antitrust risks around Ticketmaster are still unanswered rather than disproven. For investors, the message is that operations are keeping pace with the ambitious growth story that analysts have laid out in the current Narrative.
See how these catalysts shape Live Nation Entertainment’s path to a $202 fair value.
The next proof point sits in the upcoming remedies trial with state plaintiffs and any updates around the US$450m legal accrual and consent decree terms. Watch how management links future quarterly Ticketmaster adjusted operating income and international venue performance to any new conditions from that process, because that is where the Narrative’s key risk will either ease or intensify.
Add Live Nation Entertainment to your Watchlist and get alerts as these catalysts play out.
New:AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Weekly Picks

Ceazaron Buffalo Potash·12 days ago
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0631.1% undervalued
141followersusers have followed this narrative
·3commentsusers have commented on this narrative
·28likesusers have liked this narrative
JO

John_Ericon Microsoft·6 days ago
Microsoft (MSFT): The AI Bull Case Everyone Sees, Trading at a Multiple Nobody’s Willing to Pay
Fair Value:US$60011.6% undervalued
57followersusers have followed this narrative
·4commentsusers have commented on this narrative
·10likesusers have liked this narrative
MA

MarkoVTon Alphabet·9 days ago
Mo’ Money, Mo’ Problems
Fair Value:US$369.1524.4% undervalued
20followersusers have followed this narrative
·0commentsusers have commented on this narrative
·1likeusers have liked this narrative
MI

Michael_Jayon TOYO·about 1 month ago
TOYO May Be The Most Undervalued Company In The Market Today. Here’s Why:
Fair Value:US$18.470.8% undervalued
52followersusers have followed this narrative
·3commentsusers have commented on this narrative
·20likesusers have liked this narrative
M
mitchell_lawler
The Foxhole
Investors responded as though Congress will rein in the AI boom. I think economics will supersede campaign promises.
912
Mitch Lawler
Market Insights
What does rising cash burn mean for AI stocks?

Alphabet had its worst day on record after reporting, and it wasn’t alone. After three years of rewarding spending by AI stocks, the market has started to become wary of just how much that growth is really costing.
Sasha Jovanovic
Sasha is an Equity Analyst at Simply Wall St with 15 years financial markets experience. He is a CFA Charterholder and holds Bachelor degrees in Mathematics and International Studies from the University of Technology, Sydney, Australia. He worked at CommSec Investment Management as an Investment Analyst from 2014 and later at Sequoia Financial Group as a Portfolio Analyst from 2018.
About NYSE:LYV
Live Nation Entertainment
Operates as a live entertainment company worldwide.
Reasonable growth potential with adequate balance sheet.
Similar Companies
-
MSG Knickerbockers
-
NasdaqGS:SEAT
Vivid Seats
Market Insights
What does rising cash burn mean for AI stocks?MI
Mitch Lawler
What memory stocks can teach us about cyclesAN
Andrew Legget
AI has flipped the story on cybersecurity stocks, twiceMI
Mitch Lawler
Advertisement
RecentlyUpdated Narratives

MacroValue_Researchon Gulf Keystone Petroleum·about 1 hour ago
Gulf Keystone Petroleum’s Profit Margin Set to Rise by Over 14%
Fair Value:UK£8.0176.2% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
AU

Austin_Wynnon Davion Healthcare·about 3 hours ago
Davion Healthcare (NASDAQ: DAVI): A New Nasdaq Listing Pairs Home Breast Checks With a $11.6 Million Home Care Business
Fair Value:US$220.5% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
AU

Austin_Wynnon eXoZymes·about 3 hours ago
From UCLA Spinout to Product Launch: Can eXoZymes (NASDAQ: EXOZ) Turn Cell-Free Chemistry Into a Supplement Business?
Fair Value:US$23.3881.2% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives

AnalystConsensusTargeton NVIDIA·23 days ago
AI Factory Demand And Physical AI Workloads Will Drive Multi‑Year Upside Potential
Fair Value:US$328.7243.2% undervalued
1725followersusers have followed this narrative
·8commentsusers have commented on this narrative
·37likesusers have liked this narrative
ANAnalystConsensusTargeton Microsoft·6 days ago
AI Infrastructure And Cloud Commitments Will Drive Long-Term Upside For This Business
Fair Value:US$628.8115.6% undervalued
1793followersusers have followed this narrative
·2commentsusers have commented on this narrative
·15likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·about 1 month ago
AI Infrastructure And Cloud Services Will Drive Long-Term Value In This Retail Giant
Fair Value:US$330.5921.6% undervalued
1843followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative
