

Roblox (RBLX) is back in focus after its third quarter report on 29 October 2026 showed higher sales and a smaller net loss, alongside fresh detail on the company’s ongoing share repurchase activity.
That earnings update has landed in the middle of a volatile year for Roblox. The share price return has swung from a 36.82% gain over the last 90 days to a decline of 39.09% year to date, while the 1 year total shareholder return is down 51.77% and the 3 year total shareholder return is up 25.73%. This points to improving short term momentum against a mixed longer term record.
Scan how Roblox compares with other high-growth platforms by reviewing the hand-picked 19 high quality undiscovered gems that are also attracting fresh attention after recent earnings moves.
Roblox now trades almost level with the average analyst target, yet at a much wider implied discount to certain fair value estimates. That gap in opinion is where the valuation story really starts.
Most Popular Narrative: 130% Overvalued
Roblox closed at $49.31 while the most followed narrative framework puts fair value at $21.48. This represents a sharp gap that frames the current valuation debate.
A realistic case is not $95. It is probably closer to $55 to $70, with the real center of gravity around $60 to $65.
The stock can work from here, but the investment case should be built around FCF growth and dilution control, not a heroic 139x P/E on 2029 earnings.
See why 10 investors see Roblox as 130% overvalued.
Result: Fair Value of $21.48 (OVERVALUED)
Still, Roblox faces two clear pressure points: ongoing net losses of US$972.057m and the risk that heavy safety and infrastructure spending caps future margin progress.
Find out about the key risks to this Roblox narrative.
Another View: Roblox Through The SWS DCF Lens
The narrative framework pegs Roblox at a fair value of $21.48 and calls the stock overvalued at $49.31. Our DCF model reaches a very different point. It estimates future cash flows at $90.82 per share, which places the current quote at a 45.7% discount instead.
This split between story driven valuation and a cash flow based model leaves a real question on the table. Is the crowd overestimating near term risks, or is the DCF approach giving too much credit for long range forecasts that may not materialize?
For a closer look at how this cash flow based view is built, walk through the Look into how the SWS DCF model arrives at its fair value..
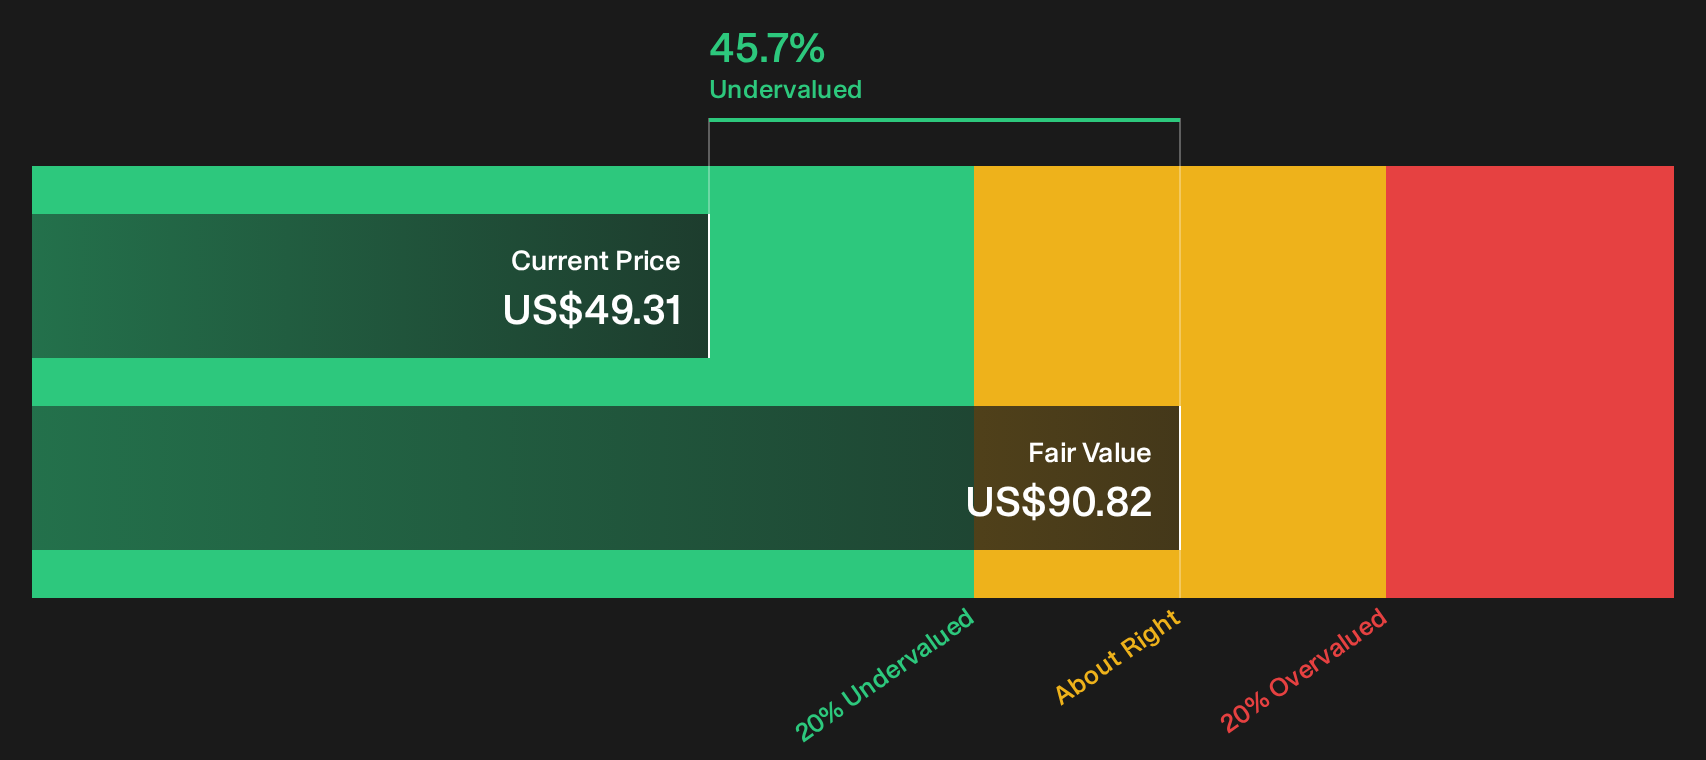
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Roblox for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
There is a complex mix of risks and rewards surrounding Roblox at the moment. Consider acting promptly, review the numbers yourself, and then carefully weigh the 2 key rewards and 2 important warning signs.
Looking for more Roblox investment ideas?
If Roblox has your attention, do not stop here. Broaden your watchlist with focused stock ideas built from clear financial filters and transparent data.
- Target potential mispricings by scanning a curated 34 high quality undervalued stocks that align strong fundamentals with appealing valuations.
- Strengthen your income stream and assess payout stability by reviewing a hand picked set of 5 dividend fortresses.
- Sleep easier through volatility by zeroing in on 31 resilient stocks with low risk scores designed to keep overall portfolio risk in check.
New:AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Weekly Picks

Ceazaron Buffalo Potash·10 days ago
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0636.8% undervalued
122followersusers have followed this narrative
·3commentsusers have commented on this narrative
·24likesusers have liked this narrative
JO

John_Ericon Microsoft·4 days ago
Microsoft (MSFT): The AI Bull Case Everyone Sees, Trading at a Multiple Nobody’s Willing to Pay
Fair Value:US$6007.3% undervalued
51followersusers have followed this narrative
·2commentsusers have commented on this narrative
·9likesusers have liked this narrative
MA

MarkoVTon Alphabet·7 days ago
Mo’ Money, Mo’ Problems
Fair Value:US$369.1524.4% undervalued
11followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
MI

Michael_Jayon TOYO·about 1 month ago
TOYO May Be The Most Undervalued Company In The Market Today. Here’s Why:
Fair Value:US$18.471.8% undervalued
33followersusers have followed this narrative
·3commentsusers have commented on this narrative
·16likesusers have liked this narrative
M
mitchell_lawler
The Foxhole
Anthropic’s IPO filing flags ‘data centers’ as a key risk area. Could the US midterms be what brings it to life?

94
Andrew Legget
Market Insights
What memory stocks can teach us about cycles

Like a wave, cycles, like what we are seeing in memory stocks, can build, change and crash. This makes understanding them an important tool for investors.
Bailey Pemberton
Bailey is an Equity Analyst at Simply Wall St with 4 years of experience as an Associate Adviser at Baywealth Financial Group, where he helped with client portfolio management, investment strategy and research. He completed a Bachelor of Commerce majoring in Finance from the University of Western Australia. As an equity analyst, Bailey provides the team with valuable insights, helping guide the creation of article content and new features like Narratives.
About NYSE:RBLX
Roblox
Operates an immersive platform for connection and communication in the United States and internationally.
Reasonable growth potential and slightly overvalued.
Similar Companies
-
NasdaqGS:TTWO
Take-Two Interactive Software
-
NasdaqGS:PLTK
Playtika Holding
Market Insights
What memory stocks can teach us about cyclesAN
Andrew Legget
AI has flipped the story on cybersecurity stocks, twiceMI
Mitch Lawler
How drones are changing the world of business, not just the battlefieldAN
Andrew Legget
Advertisement
RecentlyUpdated Narratives

DanielOliveiraon D-Wave Quantum·22 minutes ago
D-Wave will miss a Q3 revenue consensus that needs 41% growth in one quarter
Fair Value:US$10.380% overvalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
DA

Archer will beat a Q3 revenue consensus that never priced in its airport
Fair Value:US$4.120% overvalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
DA

DanielOliveiraon Lucid Group·about 3 hours ago
Lucid will miss Q3 revenue consensus because the deliveries are already known
Fair Value:US$3.0211.6% overvalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives

AnalystConsensusTargeton NVIDIA·21 days ago
AI Factory Demand And Physical AI Workloads Will Drive Multi‑Year Upside Potential
Fair Value:US$328.7239.1% undervalued
1708followersusers have followed this narrative
·8commentsusers have commented on this narrative
·37likesusers have liked this narrative
ANAnalystConsensusTargeton Microsoft·4 days ago
AI Infrastructure And Cloud Commitments Will Drive Long-Term Upside For This Business
Fair Value:US$628.8111.6% undervalued
1779followersusers have followed this narrative
·2commentsusers have commented on this narrative
·15likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·about 1 month ago
AI Infrastructure And Cloud Services Will Drive Long-Term Value In This Retail Giant
Fair Value:US$330.5919.5% undervalued
1825followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative
