
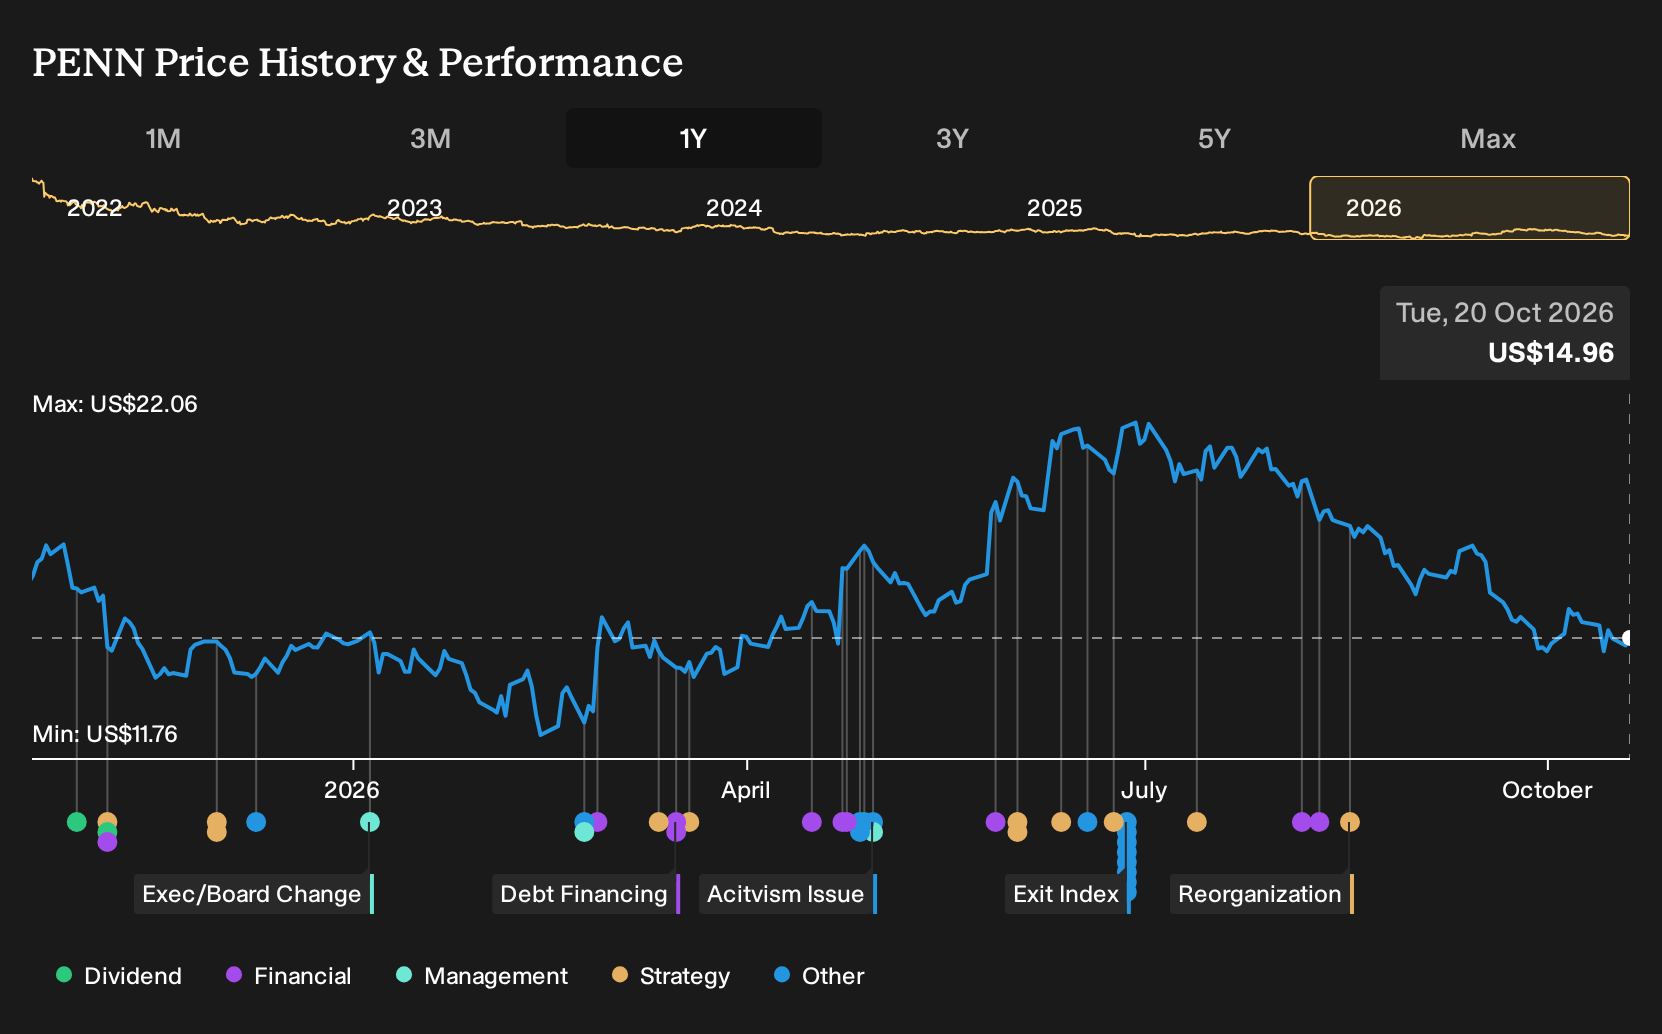
- PENN Entertainment has opposed proposed legislation in Massachusetts that would permit historical horse racing devices that function like slot machines. The company argues these terminals could shift up to US$216 million in annual gaming revenue and affect an estimated 1,074 casino jobs across the state.
- The company has recently reported earnings that exceeded consensus estimates, with an average surprise of 72.86% over the last two quarters. This highlights an operating profile where regulatory risk in key states now sits alongside stronger recent execution.
- Next, the focus will be on how PENN Entertainment’s Massachusetts regulatory headwinds intersect with its recent earnings strength to reshape the investment narrative.
Compare how other casino and leisure operators are priced relative to similar regulatory and earnings crosswinds using a curated set of 34 high quality undervalued stocks.
PENN Entertainment Investment Narrative Recap
To own PENN Entertainment, you need to believe the mix of retail casinos and interactive betting can eventually turn forecast earnings growth into consistent profitability, despite current losses of US$906.7 million. The Massachusetts historical horse racing proposal looks more like an incremental headwind than a thesis breaker, unless similar measures spread into PENN’s larger regional markets.
In the near term, the key catalyst is whether recent earnings outperformance and ESPN BET integration translate into improving digital economics while retail properties hold steady against new supply and higher state taxes. The biggest risk is that loss-making interactive operations and elevated leverage absorb cash before those projects mature.
Recent quarterly reports from PENN Entertainment that beat consensus expectations with an average surprise of 72.86% over the last two periods now sit in sharper focus next to the Massachusetts news. Stronger execution gives the business a bit more cushion if historical horse racing devices pressure slot style spend at existing casinos.
For shareholders, those earnings beats matter most if they signal better discipline around costs, promotional spend, and capital projects while the company contests regulatory changes. If future results move back in line with expectations, investors may pay closer attention to ongoing losses in Interactive, state tax increases, and competition from larger online rivals.
PENN Entertainment’s current loss of US$906.7 million compares with consensus expectations for US$466.8 million in earnings by 2029. This implies an earnings swing of about US$1.37 billion, alongside an assumed 4.9% yearly revenue growth rate that would take revenue to a projected US$8.3b in the same year.
Uncover why PENN Entertainment’s fair value indicates a 63% potential upside to its current price before that discount gap starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts frame ESPN BET as the real swing factor for PENN Entertainment, rather than Massachusetts slot style competition. Before this news, the bullish camp was modeling revenue reaching about US$8.9b and earnings of roughly US$741.9 million by 2029. That is far above consensus, and these views may shift as the regulatory story evolves.
Explore 4 other PENN Entertainment fair value estimates, including one that suggests as much as 596% upside from the current price!
Form Your Own Verdict
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your PENN Entertainment research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PENN Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PENN Entertainment’s overall financial health at a glance.
Looking for more PENN Entertainment sized investment ideas?
If you want to pressure test your thesis on PENN Entertainment and widen your opportunity set at the same time, use the Simply Wall St Screener to see how other businesses stack up on valuation, quality, and risk.
- For investors who want potential value coupled with resilience, compare PENN Entertainment with a 31 resilient stocks with low risk scores that already clear strict risk filters.
- If you prefer stronger balance sheets that may handle earnings volatility more comfortably, line PENN up against a list of solid balance sheet and fundamentals (25 results) and see which ones fit your comfort zone.
- Those hunting for less crowded ideas can broaden their watchlist with a focused 21 high quality undiscovered gems that pair quality fundamentals with relatively limited market attention.
New:Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Weekly Picks

Ceazaron Buffalo Potash·29 days ago
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0631.1% undervalued
86followersusers have followed this narrative
·2commentsusers have commented on this narrative
·19likesusers have liked this narrative
AN

andrei9868on Zscaler·6 days ago
Zscaler: The Market May Still Be Treating AI Security As An Add-On. Management Is Betting It Becomes The Platform.
Fair Value:US$249.9714.2% undervalued
13followersusers have followed this narrative
·0commentsusers have commented on this narrative
·1likeusers have liked this narrative
JO

joehanncsad2717on BTQ Technologies·about 2 months ago
Quantum-Era Security Transition: Preparing for Q-Day
Fair Value:CA$25.5887.9% undervalued
13followersusers have followed this narrative
·0commentsusers have commented on this narrative
·3likesusers have liked this narrative
CE

CentryResearchon General Dynamics·6 days ago
General Dynamics: A Decade of Submarines, at a Discount
Fair Value:US$370.927.1% undervalued
5followersusers have followed this narrative
·1commentusers have commented on this narrative
·3likesusers have liked this narrative
M
mitchell_lawler
The Foxhole
All eyes are on the AI giants this earnings season. The biggest surprises might come from somewhere else.
How drones are changing the world of business, not just the battlefield

Drones are more than just toys. They are now changing the face of numerous industries. We take a look into the wide world of drones.
62
Oct 16, 2026
About NasdaqGS:PENN
PENN Entertainment
Provides integrated entertainment, sports content, and casino gaming experiences in the United States and internationally.
Very undervalued with moderate growth potential.
Similar Companies
-
Flutter Entertainment
-
NasdaqGS:DKNG
DraftKings
Market Insights
How drones are changing the world of business, not just the battlefieldAN
Andrew Legget
Which experience stocks actually have pricing power?CH
Chrissy Paradis
AI agents are redrawing competitive moatsMI
Mitch Lawler
Advertisement
RecentlyUpdated Narratives

MarkoVTon SK hynix·about 2 hours ago
History suggests uneven track record
Fair Value:US$450.4569.0% undervalued
2followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
LU

LunaRodason Netflix·about 6 hours ago
Netflix : What They Said vs. What They Did
Fair Value:US$123.8744.5% undervalued
2followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
LE

Ledoraon NVIDIA·about 10 hours ago
NVIDIA (NVDA): Still Watching the AI Growth Story, but Is the Stock Getting Harder to Value?
Fair Value:US$50557.1% undervalued
8followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives
ANAnalystConsensusTargeton NVIDIA·6 days ago
AI Factory Demand And Physical AI Workloads Will Drive Multi‑Year Upside Potential
Fair Value:US$328.7234.1% undervalued
1635followersusers have followed this narrative
·8commentsusers have commented on this narrative
·37likesusers have liked this narrative
AN

AnalystConsensusTargeton Microsoft·3 days ago
AI Infrastructure And Cloud Commitments Will Drive Long-Term Upside For This Business
Fair Value:US$599.2411.2% undervalued
1721followersusers have followed this narrative
·1commentusers have commented on this narrative
·15likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·17 days ago
AI Infrastructure And Cloud Services Will Drive Long-Term Value In This Retail Giant
Fair Value:US$330.5920.6% undervalued
1769followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative

1 Comment
Pingback: TWICE member Jihyo leaves JYP Entertainment after 21 years, establishes her own agency EMITHAUS - Comic Vibe