
Flutter Entertainment has seen its stock slide sharply over the past year, and that slump now puts a spotlight on a simple question. Is the current share price in any way justified by the sales the business is generating?
- Over the past 12 months, Flutter Entertainment shares have fallen 64.3%. This puts recent market confidence in the business under scrutiny when you compare it with what the company is actually selling.
- Fresh headlines around potential regulatory clarity for sports prediction markets in the US may support expectations for how quickly Flutter can grow its betting turnover and convert that into future revenue.
- Your read on Flutter Entertainment is one view; the desks covering it have another. See what analysts think Flutter Entertainment’s shares could be worth.
The issue now is whether Flutter Entertainment’s recent share price reflects a sensible multiple of its sales.
If you are questioning whether Flutter Entertainment’s current price lines up with its sales, it can help to compare it with a wider group screened for 34 high quality undervalued stocks.
Does Flutter Entertainment Look Undervalued on Sales?
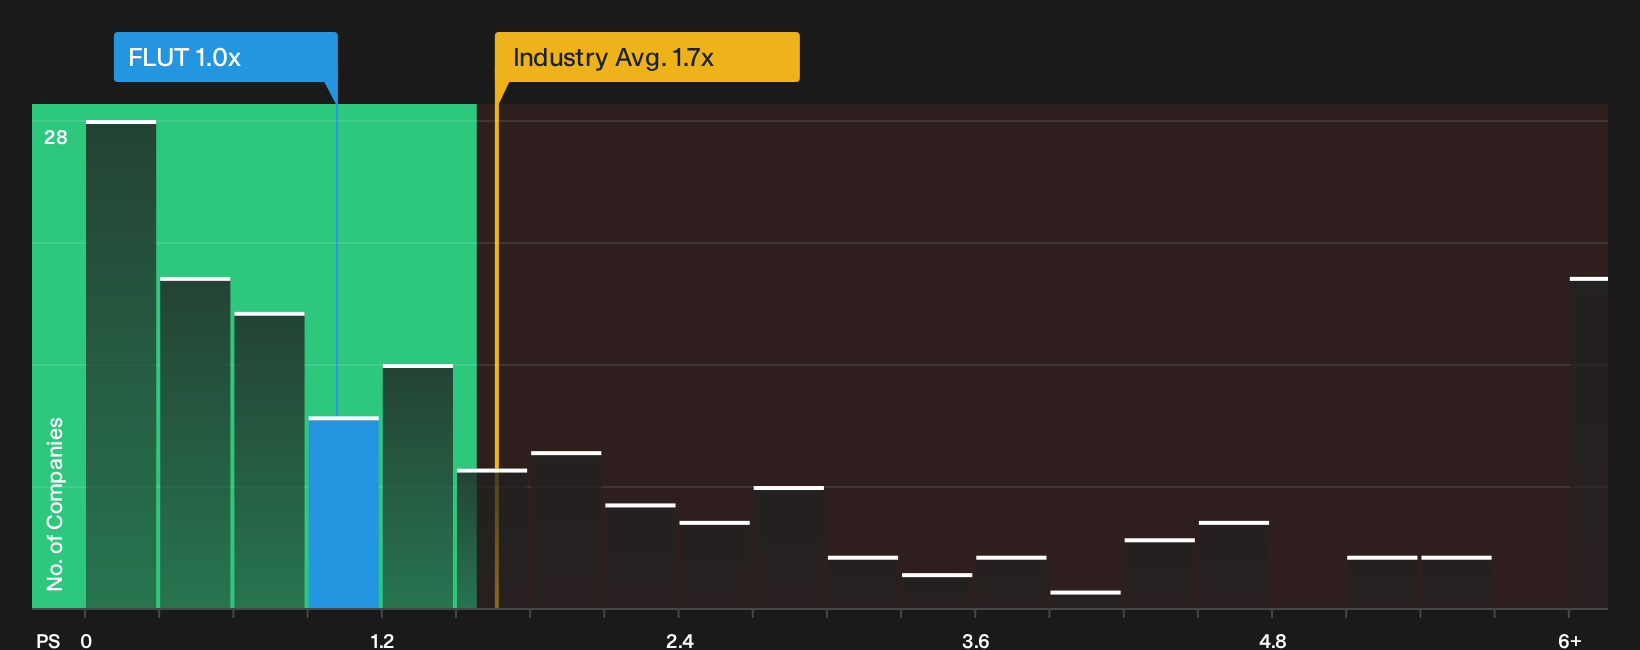
The P/S ratio suits Flutter Entertainment because investors often focus on revenue-based gauges for online betting platforms where bottom line earnings can be volatile. On this yardstick, the stock trades on a P/S of 1.0x, which is lower than the broader hospitality sector average of 1.7x and also below peers at 1.4x. That puts the share price at a lower revenue multiple than both the sector and a group of similar businesses.
Fresh headlines around the potential for clearer US sports prediction market rules have lifted interest in Flutter Entertainment, yet the current P/S still screens below the level implied by a more tailored fair-value multiple that blends the company’s own risks, margins and growth profile. For a reader weighing the recent share price slide against this revenue-based metric, the gap to that benchmark suggests the stock trades at a discount on sales. Explore the numbers behind Flutter Entertainment’s P/S valuation.
The Flutter Entertainment Narrative: What Would Justify Today’s Price?
Simply Wall St Narratives take the valuation puzzle around Flutter Entertainment and spell out the specific future paths for growth, margins and earnings that would need to play out for the stock to look meaningfully higher or lower than today’s price on the Community page. Each scenario connects its implied number to a clear view on where Flutter Entertainment’s growth, profitability and risk profile could head next, giving you a reference point you can revisit as fresh information comes through.
The Flutter Entertainment community splits between one group that sees upside from prediction markets and iGaming, and another that worries those same themes cap returns.
“Product innovation, particularly in live betting and personalized betting features (e.g., “Your Way Parlay,” Same Game Parlay Live, and platform migrations across Snai and FanDuel), positions Flutter to capture greater user engagement and wallet share, supporting both revenue growth and long-term margin expansion…”
Discover why this Narrative puts Flutter Entertainment at 28% undervalued.
“Despite FanDuel’s scale leadership in U.S. Sportsbook and an improving product mix in NBA and parlays, persistently elevated promotional intensity and competitors’ willingness to spend uneconomically could structurally compress unit economics, limiting contribution margin and slowing the pace of earnings growth…”
Explore why this Narrative puts Flutter Entertainment at 25% overvalued.
One more check on Flutter Entertainment that sits beyond the price tag
Before you move on from Flutter Entertainment, it is worth knowing that analyst projections for revenue and earnings a few years out provide a separate reference point to compare with today’s multiples. Explore where analysts expect Flutter Entertainment to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New:AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Oil routes are being dismantled one by one. The durable winner could be the North American energy left standing.
The durable premium you describe does not really exist for crude in a liquid market. This scenario, in almost a similar form, is happening thrice this year.
Persistent volatility raises the hurdle rate on every long-lived energy investment, which suppresses the supply response that would eventually fix the problem. The instability is self-perpetuating in a way the price level is not.

Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that’s not always a bad outcome for shareholders.
14
Sep 11, 2026
About NYSE:FLUT
Flutter Entertainment
Operates as a sports betting and gaming company in the United States, the United Kingdom, Ireland, Australia, Italy, and internationally.
Undervalued with moderate growth potential.
Similar Companies
-
NasdaqGS:DKNG
DraftKings
-
MGM Resorts International
Market Insights
Are social media stocks the new Big Tobacco?AN
Andrew Legget
What 13F filings won’t tell you about a billionaire’s stock picksMI
Mitchell Lawler
Great earnings season, but are the earnings real?AN
Andrew Legget
Advertisement
Weekly Picks

Ceazaron Sparc AI·20 days ago
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2541.1% undervalued
194followersusers have followed this narrative
·0commentsusers have commented on this narrative
·29likesusers have liked this narrative
CO

composite32on Archrock·7 days ago
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.9% undervalued
3followersusers have followed this narrative
·0commentsusers have commented on this narrative
·1likeusers have liked this narrative
JO

John_Ericon Advanced Energy Industries·16 days ago
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8655.9% undervalued
5followersusers have followed this narrative
·0commentsusers have commented on this narrative
·3likesusers have liked this narrative
IS

isidrohgon Lam Research·5 days ago
The Memory Shortage Is Lam’s Order Book
Fair Value:US$423.8536.1% undervalued
3followersusers have followed this narrative
·0commentsusers have commented on this narrative
·2likesusers have liked this narrative
RecentlyUpdated Narratives

Clive_Thompsonon Upside Gold·about 2 hours ago
Upside Gold – New Technical Report Expected in Q1 2027 Could Re-Rate The Stock.
Fair Value:CA$1.552.7% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
FR

FRAGMENTSon SITE Centers·about 9 hours ago
SITE Centers Trades Around $2.90. It Had $238.9 Million of Cash. One $129.6 Million Decision Changes the Outcome.
Fair Value:US$3.313.3% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
WA

waioaon UUE Holdings Berhad·about 11 hours ago
UUE Holdings Expands Into High-Voltage Power Infrastructure Through Strategic JV
Fair Value:RM 1.559.7% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives

AnalystConsensusTargeton NVIDIA·about 2 months ago
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8329.9% undervalued
1450followersusers have followed this narrative
·8commentsusers have commented on this narrative
·35likesusers have liked this narrative
AN

AnalystConsensusTargeton Alphabet·4 months ago
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8919.4% undervalued
1628followersusers have followed this narrative
·0commentsusers have commented on this narrative
·19likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·about 1 month ago
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32724.0% undervalued
1644followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative
