

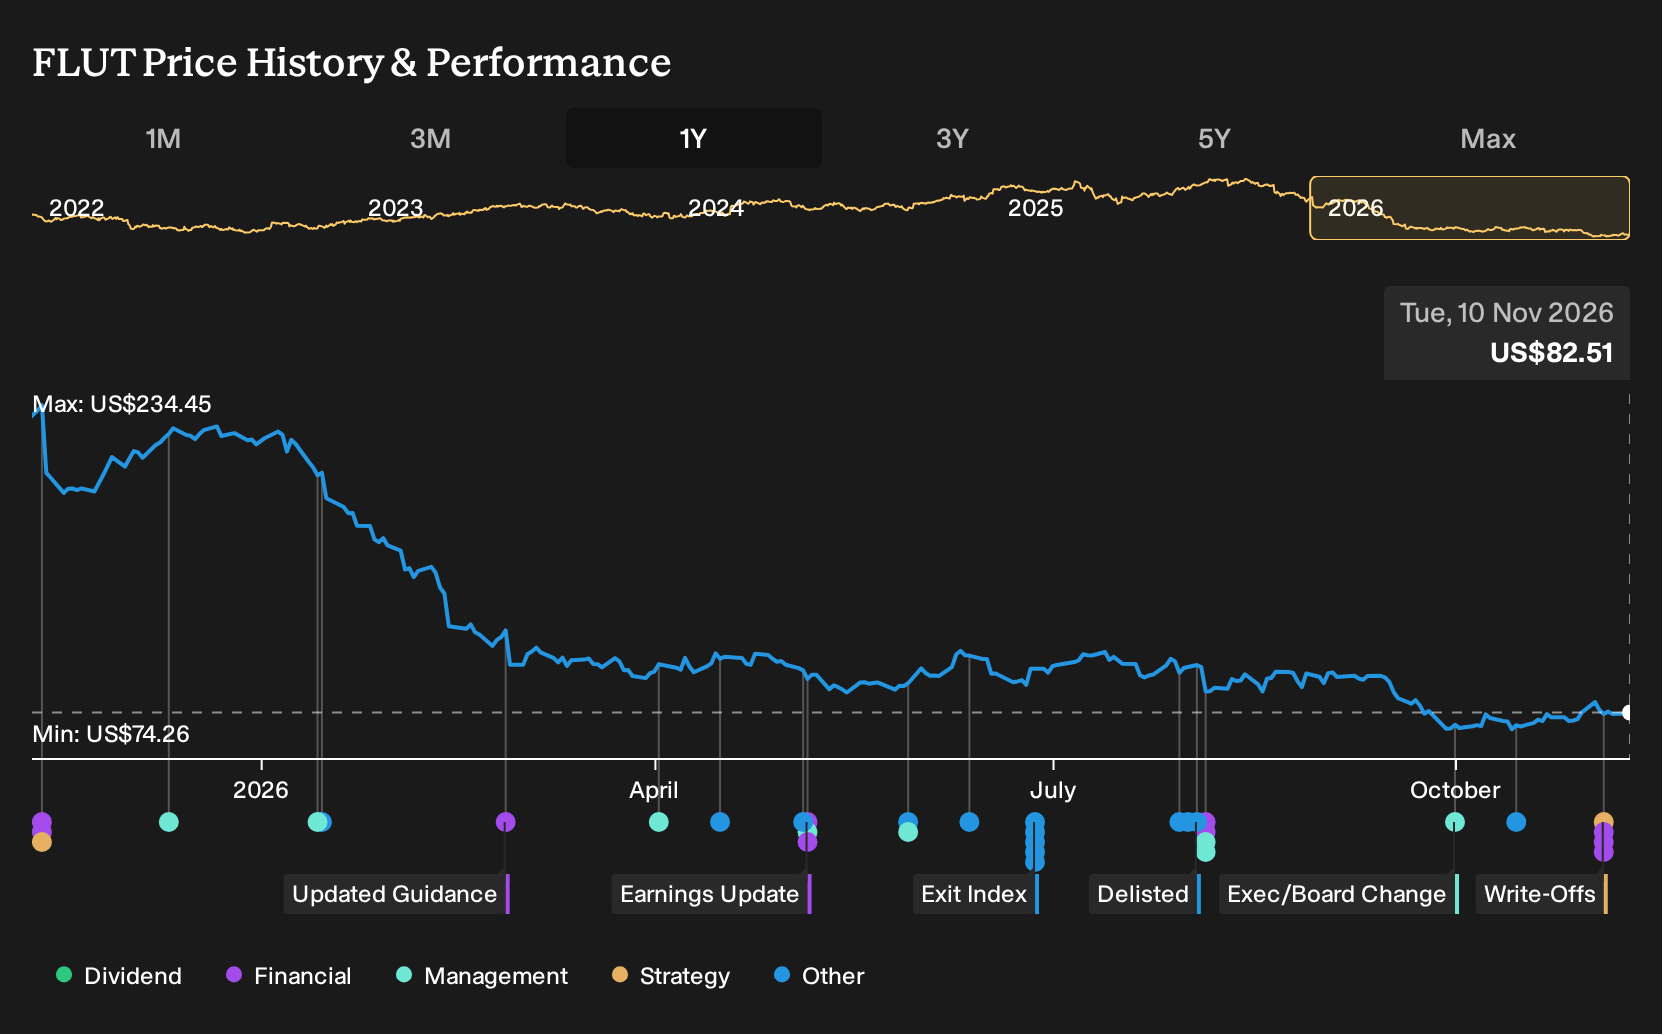
- Flutter Entertainment reported Q3 2026 sales of US$3.874b and a net loss of US$862m, booked US$873m of Brazil related impairments, and lowered full year 2026 revenue guidance to a midpoint of US$17.61b.
- The Brazil goodwill and long lived asset write downs, triggered by a government ban on fixed odds sports betting and online gaming, highlight how regulatory shifts can quickly reshape Flutter Entertainment’s international earnings mix and capital allocation priorities.
- Next, the focus turns to how Flutter Entertainment’s investment narrative holds up when weighed against Q3 losses and the Brazil impairment shock.
Spot potential beneficiaries of this kind of regulatory shake up by scanning our hand picked 30 resilient stocks with low risk scores, which may offer a different balance of earnings stability and downside protection.
Advertisement
Flutter Entertainment Investment Narrative Recap
To back Flutter Entertainment after this quarter, you need to believe the core online betting and iGaming franchises in the US, UK, Italy and Australia can offset hits from tougher rules in places like Brazil. The latest Brazil impairment and widened Q3 loss test that belief, but they do not remove it entirely.
Right now, the key near term swing factor is operational execution in regulated growth markets such as the US. In that market, management said the sportsbook outperformed internal expectations. The biggest risk is that Brazil is not an isolated case and that higher taxes or outright bans in other regions keep pressure on earnings and capital deployment.
The most relevant fresh disclosure is the US$873m impairment in Brazil. That charge, driven by a ban on fixed odds sports betting and online gaming, directly collides with the analyst consensus Narrative on Simply Wall St. That consensus assumed Brazil would be a growth engine through regulatory liberalization and integration benefits.
That earlier Narrative leaned on expansion in newly regulated jurisdictions, cost synergies from deals like NSX in Brazil, and more efficient marketing to improve margins. The ban in Brazil instead highlights regulatory risk as a live catalyst. For you, the question becomes how much of the long term story now rests on markets such as the US and Italy, where execution, product depth and cost control matter even more.
Flutter Entertainment’s current analyst narrative points to revenues of US$21.9b and earnings of US$851.8m by 2029, built on forecast annual revenue growth of 8.5% and an earnings swing of about US$1.61b from today’s loss of US$754.0m.
Discover how Flutter Entertainment’s fair value indicates a 53% potential upside to its current price, which could materialize sooner than many investors expect.
Exploring Other Perspectives
You can see how sharply opinions on Flutter Entertainment split when you look at the bullish catalyst of U.S. prediction markets and FanDuel loyalty. Before this Brazil hit, the most optimistic analysts were pencilling in US$23.5b of 2029 revenue and US$2.1b of earnings. That is far above the consensus view and could shift again after this impairment.
Explore 3 other Flutter Entertainment fair value estimates, including one that suggests as much as 117% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Flutter Entertainment research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Flutter Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flutter Entertainment’s overall financial health at a glance.
Looking For More Ideas Beyond Flutter Entertainment?
If the Brazil shock has you reassessing risk, it can help to widen the lens and compare Flutter Entertainment with other businesses that have very different earnings drivers and balance sheet profiles. The Simply Wall St Screener lets you scan the market through multiple filters so you can line up alternatives that better match your risk tolerance and income goals.
- If you want potential upside with strict risk controls, start with a curated set of resilient companies in the 30 resilient stocks with low risk scores that aim to limit downside while still leaving room for growth.
- If balance sheet strength matters most to you, focus on businesses backed by robust finances through our list of solid balance sheet and fundamentals (24 results), which highlights companies with healthier gearing and fundamentals.
- If you are hunting for opportunities that are less crowded, look over the 20 high quality undiscovered gems that pair strong underlying metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
Weekly Picks

Austin_Wynnon First Breach·19 days ago
First Breach: Ammo Today. Drones Next. Why This America First Company Could Easily Double in Price
Fair Value:US$2.867.3% undervalued
36followersusers have followed this narrative
·0commentsusers have commented on this narrative
·6likesusers have liked this narrative
AN

ANTONI0on PepsiCo·13 days ago
PepsiCo at $135: A 4.4% Yield, an Activist, and Why the Maths Still Says Wait for $95
Fair Value:US$1440.3% undervalued
4followersusers have followed this narrative
·0commentsusers have commented on this narrative
·1likeusers have liked this narrative
AN

Andrei_Niculescuon Talen Energy·5 days ago
Talen: Selling Tomorrow’s PJM Capacity to Buy Back Today — 2027 Guide Is Real, but So Is the Leverage and the Hedge Book
Fair Value:US$3958.6% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
CO

Composite_Researchon Eaton·2 months ago
“Grid-to-Chip: How Eaton Controls the Physical Bottlenecks of AI Data Centers”
Fair Value:US$517.0631.5% undervalued
27followersusers have followed this narrative
·3commentsusers have commented on this narrative
·9likesusers have liked this narrative
Curated watchlists
Bailey Pemberton
Bailey is an Equity Analyst at Simply Wall St with 4 years of experience as an Associate Adviser at Baywealth Financial Group, where he helped with client portfolio management, investment strategy and research. He completed a Bachelor of Commerce majoring in Finance from the University of Western Australia. As an equity analyst, Bailey provides the team with valuable insights, helping guide the creation of article content and new features like Narratives.
