
AMC Entertainment Holdings (AMC) has launched a major balance sheet reset, pricing US$2.0b in first lien notes, arranging new term loans, and running a cash tender offer to retire older secured debt.
AMC Entertainment Holdings has seen momentum build through 2026, with a 90 day share price return of 44.83% and an 82.61% share price gain year to date, while the 5 year total shareholder return is still down 98.59%.
Surf 16 high quality undiscovered gems that, like AMC Entertainment Holdings after its refinancing push, pair bold balance sheet moves with underlying fundamentals that may not yet be fully appreciated by the market.
AMC Entertainment Holdings now trades only fractionally below the average analyst target, yet sits at a deeper discount to some fair value estimates. Is that a misread of its refinancing play, or a rational safety margin on a loss-making business?
Most Popular Narrative: 2% Overvalued
Against a last close of $2.94, the most followed fair value estimate for AMC Entertainment Holdings sits at $2.88, implying a small premium that hinges on how much faith investors place in its premium cinema and debt clean up story.
AMC’s strategic focus on closing underperforming theaters while opening high-margin, high-revenue locations in vibrant, urban centers and leveraging data-driven pricing is improving portfolio profitability and operational efficiency, positively impacting net margins and operating cash flow.
See why 39 investors see AMC Entertainment Holdings as 2% overvalued.
Result: Fair Value of $2.88 (OVERVALUED)
Still, AMC Entertainment Holdings carries heavy debt and ongoing equity dilution risk, so any setback in box office trends could quickly challenge this optimistic narrative.
Find out about the key risks to this AMC Entertainment Holdings narrative.
Another View On AMC Entertainment Holdings Valuation
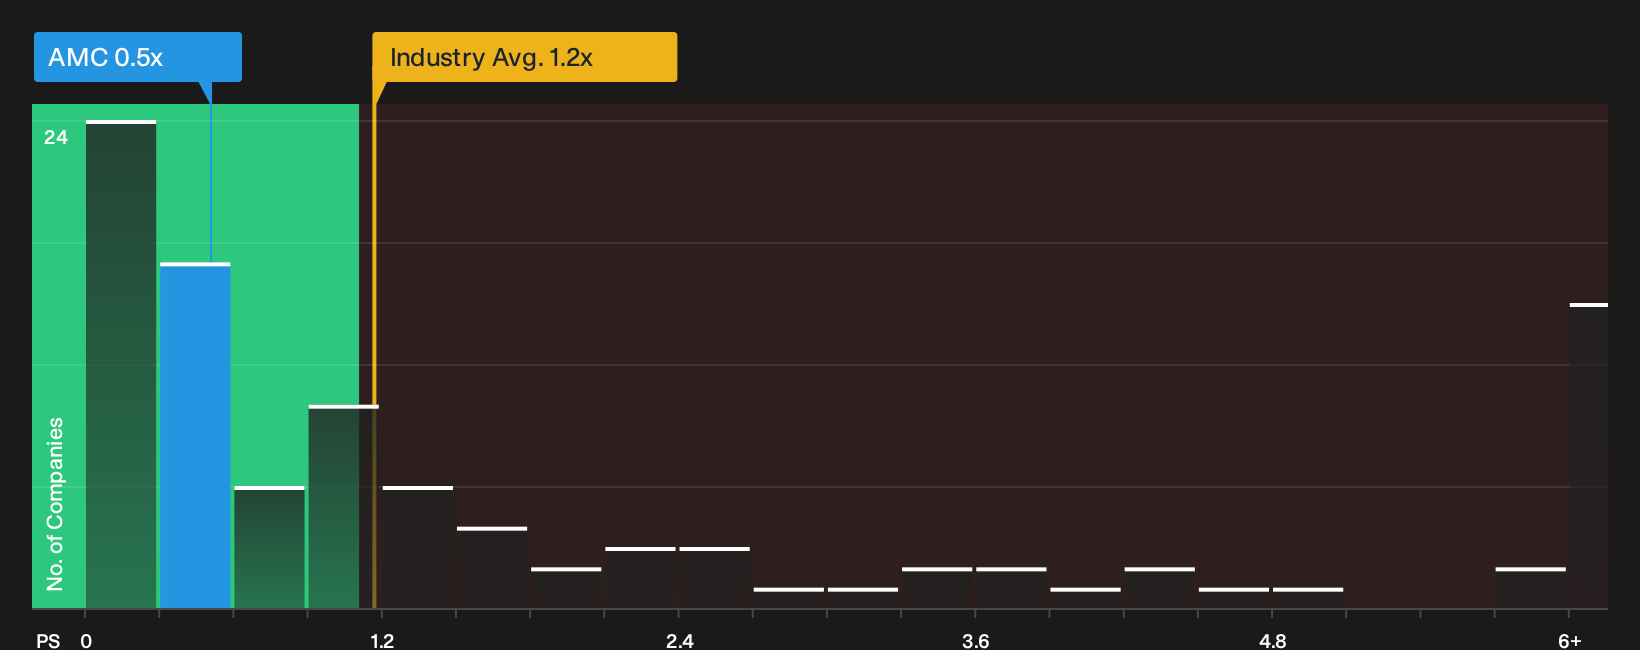
While the consensus fair value narrative pegs AMC Entertainment Holdings at $2.88 and labels the stock as slightly overvalued, the preferred P/S yardstick tells a different story. AMC trades on a P/S ratio of 0.5x, compared with a 0.8x fair ratio, a 1.2x sector average, and a 4.3x peer group level. That gap points to a marked valuation discount. The open question is whether this reflects lingering balance sheet and dilution concerns, or an opening for investors who think the business can stabilize.
To unpack what this gap in P/S ratios might mean for your own risk tolerance and time horizon, it is worth taking a closer look at the underlying valuation breakdown rather than focusing only on the headline fair value number. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about whether AMC Entertainment Holdings is being priced too cautiously or not cautiously enough right now? Act quickly on that instinct and pressure test it against the underlying data, including 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond AMC Entertainment Holdings?
If AMC Entertainment Holdings has you rethinking what risk and reward look like, do not stop there. Broaden your watchlist with ideas filtered for quality, value, and staying power using the Simply Wall St screener.
- Spot potential turnarounds early by scanning 6 elite penny stocks with strong financials where tiny market caps meet tighter balance sheets and cleaner financial profiles than many would expect.
- Target compelling price tags by reviewing 32 high quality undervalued stocks that pair solid fundamentals with valuations that look conservative on multiple metrics.
- Prioritize resilience by filtering for 30 resilient stocks with low risk scores so you focus on businesses with steadier risk scores rather than chasing every market swing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New:Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
The old reason to buy emerging markets was their young, growing populations. Most of them aren’t young anymore.
I was never a fan of emerging markets investing tbh. Good companies are everywhere.
The best EM bet might be the AI companies. Most emerging markets will consume this rather than build the frontier layer, and consuming it is where the real economic gain is. Leapfrogging to AI-delivered services without the legacy infrastructure is a bigger jump than upgrading existing systems. The benefit accrues locally, the earnings accrue to the supplier.
Where to invest when populations stop growing

Artificial intelligence can do a lot for production. But consumption is a different issue, and changing demographics aren’t helping. So where do you invest when populations aren’t growing?
10
Sep 24, 2026
About NYSE:AMC
AMC Entertainment Holdings
Engages in the theatrical exhibition business in the United States and internationally.
Good value with slight risk.
Similar Companies
-
Cinemark Holdings
Market Insights
Where to invest when populations stop growingAL
Alegget
What happens to energy stocks as the fix gets built?MI
mitchell_lawler
Are social media stocks the new Big Tobacco?AL
Alegget
Advertisement
Weekly Picks

Ceazaron Buffalo Potash·5 days ago
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0613.2% undervalued
40followersusers have followed this narrative
·0commentsusers have commented on this narrative
·10likesusers have liked this narrative
TO

Tokyoon Novo Nordisk·about 2 months ago
EU#2 – From Humble Beginnings to Global Powerhouse
Fair Value:DKK 851.0470.3% undervalued
83followersusers have followed this narrative
·19commentsusers have commented on this narrative
·27likesusers have liked this narrative
HA

HarishPKon Zoetis·28 days ago
Decision Making Under Ambiguity – A Case Study on Expectations Investing
Fair Value:US$91.322.2% undervalued
13followersusers have followed this narrative
·1commentusers have commented on this narrative
·6likesusers have liked this narrative
RE

RedCandleRxon AppLovin·11 days ago
Why the Market Still Misprices AppLovin as Just a Gaming Network
Fair Value:US$50738.7% undervalued
19followersusers have followed this narrative
·1commentusers have commented on this narrative
·8likesusers have liked this narrative
RecentlyUpdated Narratives

ANTONI0on SEEK·about 3 hours ago
SEEK Limited (ASX: SEK). A 63% Drawdown, and the One Question That Decides It
Fair Value:AU$10.455.9% overvalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
ES

Estebanon Copart·about 8 hours ago
CPRT 04-2026
Fair Value:US$18.9745.4% overvalued
3followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
J_

J_Tyraderon Sezzle·about 12 hours ago
Sezzle: Trading 41% below what it’s worth
Fair Value:US$187.8840.7% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives

AnalystConsensusTargeton NVIDIA·about 2 months ago
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8325.7% undervalued
1512followersusers have followed this narrative
·8commentsusers have commented on this narrative
·35likesusers have liked this narrative
AN

AnalystConsensusTargeton Alphabet·2 days ago
AI Demand Must Outrun Infrastructure Buildout
Fair Value:US$429.4619.9% undervalued
1664followersusers have followed this narrative
·0commentsusers have commented on this narrative
·19likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·about 1 month ago
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.6% undervalued
1681followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative
